How Much Business Loan Can I Afford in Australia? SME Cash Flow Planning Guide
19 February 2026
Imagine your small business facing a rush of orders. Stock runs low, wages loom, and suppliers demand payment. You need funds fast. But ask for too much, and repayments could strain your cash flow to breaking point. Ask for too little, and the opportunity slips away. Getting SME cash flow and borrowing right starts with smart business funding amount planning in Australia. This guide helps you think through a sensible enquiry amount. It is planning, not a credit decision.
Start with the Job at Hand
Before pondering how much business loan can I afford in Australia, nail down the purpose. Funds serve specific needs: restocking inventory ahead of peak season, buying equipment to boost output, bridging payroll gaps from late invoices, or gearing up for expansion. Pinpoint the amount tied to that goal and the timeframe.
Think of a retailer ordering extra stock for Christmas trade. They might sketch a $50,000 need for inventory – purely an illustration to map thinking, not a guaranteed facility. Over what months will it repay from sales? Clarity here shapes your enquiry range.
Map Your Cash Cycle in the Australian Context
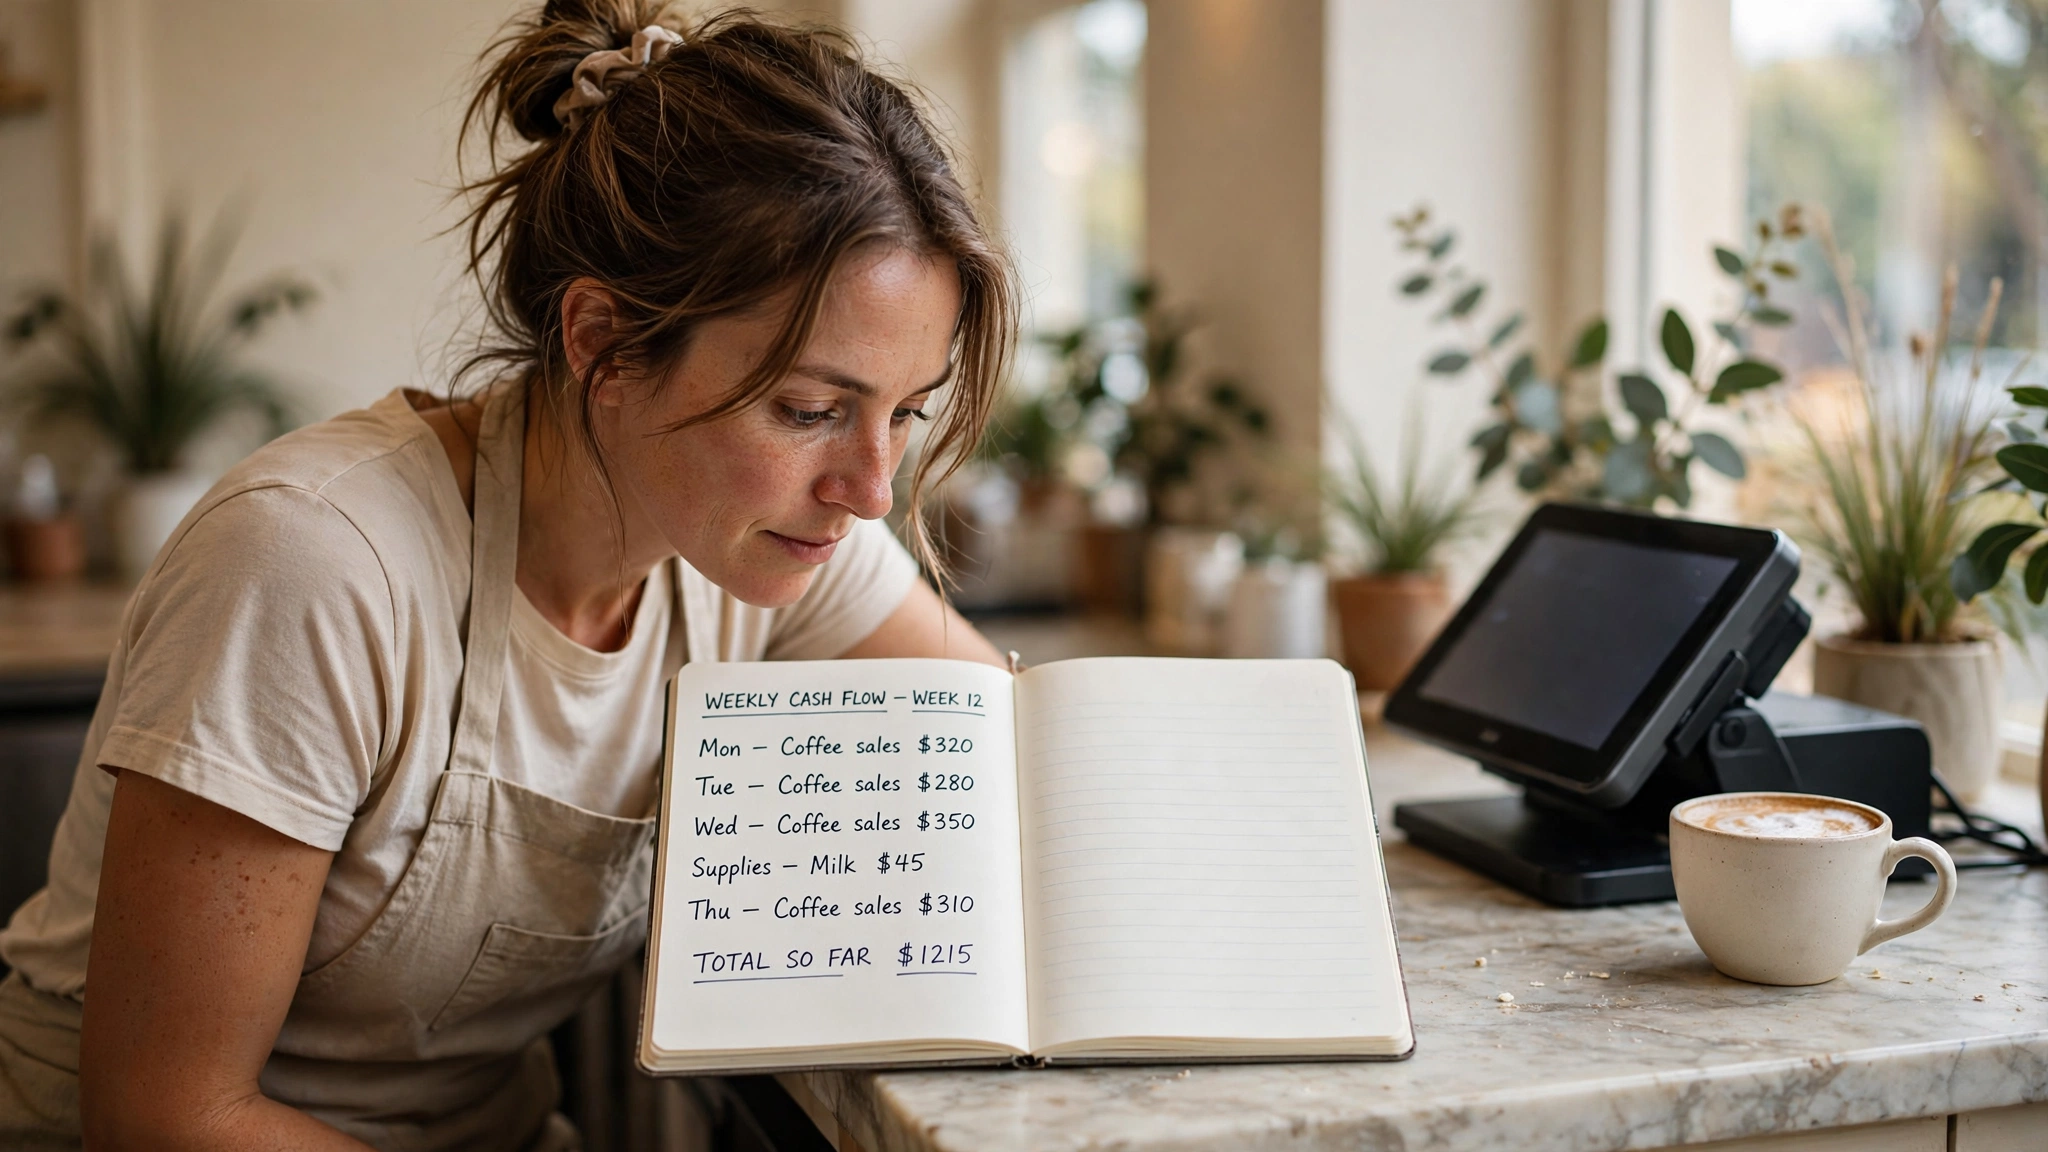
Australian SMEs live by their cash cycle. Invoices sit at 30, 60, or 90 days. BAS and GST lodgements pull cash quarterly. Wages hit fortnightly. Suppliers often chase weekly terms. Plot these on a calendar or spreadsheet. Bank statements over three to six months reveal patterns better than a single profit figure.
Key Cycle Questions
- When do customers pay, and how reliably?
- What are your fixed outflows: rent, utilities, superannuation?
- Does GST timing create dips?
This map shows where funding fits without disrupting the flow.
Spot Your Surplus Cash
Surplus means cash left after essentials. Cover wages, tax obligations, existing repayments, GST set-asides, and stock buys first. What remains? Bank statements paint this picture plainly, often clearer than paper profits which ignore timing.
Ask yourself: After those commitments, could I handle an extra outflow, say $2,000 monthly from a hypothetical facility? This is a thinking tool. Chat with your accountant for precise cash-flow modelling, especially around tax and deductions.
Account for Existing Debt and Seasonality
List current loans, credit cards, or ATO payment plans. Quiet months hit harder – hospitality in winter, retail post-holidays. Test your surplus across low periods. Seasonality explains why some enquiries suit shorter facilities.
Why Providers Size Facilities Differently
Providers assess based on product type, security offered, and trading history. Unsecured lines might cap lower than asset-backed options. Longer histories open bigger facilities. Each sets its limits. Your enquiry purpose and cash flow story guide their interest.
Choose a Sensible Enquiry Amount
Pick a range you can justify, linked to use of funds. $40,000 to $60,000 for that stock illustration beats a vague $50,000. Explain the plan. Enquiry is not an application – providers decide fit.
Make an Enquiry with FundingMatch
FundingMatch lets you submit amount and purpose simply. Unsure? Note it. With your consent, your enquiry may be shared with selected providers or brokers who may contact you. There is no obligation to proceed.
FAQ: Business Funding Amount Planning in Australia
Does this calculate how much I can borrow?
No. This is a planning guide. FundingMatch does not assess capacity or approve amounts.
What if my cash flow varies?
Focus on troughs. Accountants help model this.
Is an enquiry binding?
No. Providers choose to engage.
Ready to plan your next move? Start an enquiry at FundingMatch today.
Strong disclaimer: This guide offers general planning thoughts, not financial advice, serviceability checks, or borrowing capacity calculations. FundingMatch connects enquiries to providers who make their own decisions. Consult professionals for your situation.