Invoice Finance Australia: Managing Cash Flow from Slow-Paying Customers
15 January 2026
Picture a busy Sydney wholesaler wrapping up a large order for a retail chain. The invoice lands in the client's inbox, undisputed and for a healthy sum. Yet their payment terms stretch to 90 days. Subcontractors knock for their share today, staff expect wages tomorrow, and the ATO awaits GST this quarter. Cash feels locked away, even as work keeps flowing.
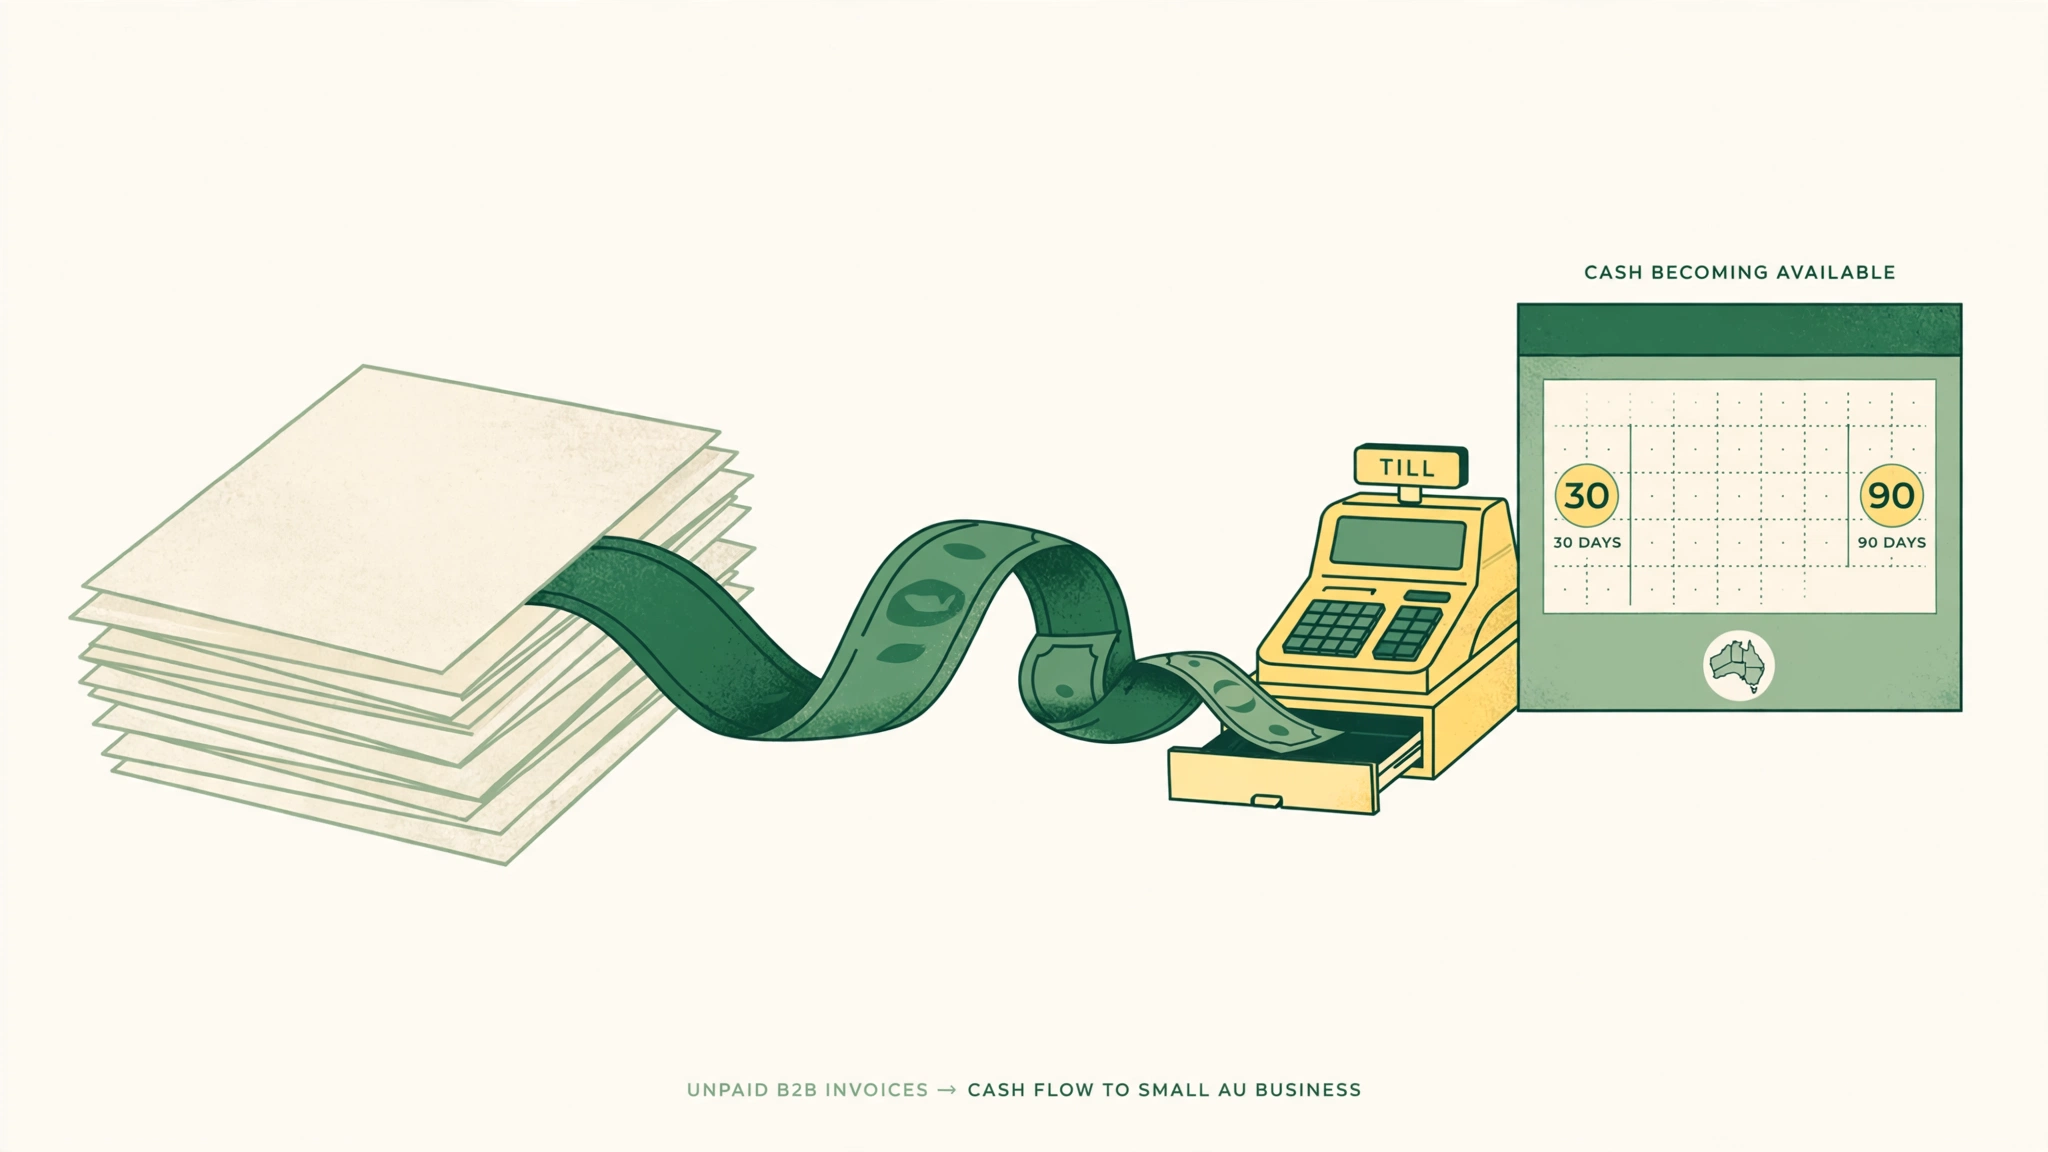
This scenario plays out across Australian trades, manufacturing, professional services, and wholesale businesses. Slow-paying customers disrupt business cash flow, turning solid sales into temporary headaches. Invoice finance is one option some businesses enquire about to access cash tied up in unpaid B2B invoices.
It's not a loan against assets or future sales. Instead, it centres on verified invoices from creditworthy customers. Providers may advance cash against these, helping smooth operations without waiting for customer payments.
How Invoice Finance Often Works in Practice
In simple terms, a provider reviews your unpaid B2B invoices. If they meet certain criteria, they may agree to advance a portion of the invoice value. The exact amount depends on their assessment of the invoices, your customers, and your business.
If a provider offers a facility, timing, fees and settlement steps are set in their own terms. When your customer pays, either to the provider or via you, the invoice is usually marked as settled and any remaining balance, less agreed fees, returns to your business.
Structures vary. Some resemble invoice factoring, where the provider takes over collections. Others look like invoice discounting, staying behind the scenes. But labels and details differ between providers. Invoice factoring vs invoice discounting Australia often boils down to customer notification and control, yet no single model fits all.
When Invoice Finance May Suit Your Business Cash Flow Needs
This approach may help if you serve established B2B customers on 30-90 day terms. Think manufacturers supplying retailers, electricians billing builders, or consultants invoicing corporates. A steady stream of approved invoices, with cash needed upfront for growth or bills, often aligns well.
- Solid trading history with reliable payers.
- Multiple customers, avoiding over-reliance on one.
- Growth demands, like stocking up before big orders.
It may not fit consumer-facing invoices, disputed bills, or brand-new customer relationships without payment history. Providers assess each case individually, so outcomes vary.
What Providers Typically Review
Expect questions about your customers' credit strength, invoice ages, and payment patterns. They look at your ABN, trading records, and debtor concentration. Is one client 80% of receivables, or spread across dozens? All this informs their decision on eligibility and terms.
No universal checklists exist. Sharing sample invoices and debtor lists during enquiries helps providers respond accurately.
Understanding the Costs Involved
Providers set fees and interest based on risk, invoice size, and term length. These might include service charges or rates applied to advanced funds. Compare this to alternatives: overdraft costs, supplier discounts forgone, or growth stalled by waiting.
Shop around by asking multiple providers for their structure. Weigh the certainty of cash now against holding out for full payments later.
Customer Notification: A Key Consideration
Some arrangements notify customers that payments go to the provider. Others keep it confidential, with you collecting and remitting. Ask upfront: how does this work, and what does it mean for client relationships? Transparency varies, so clarify early.
Enquiring via FundingMatch
Invoice finance is one category on the FundingMatch enquiry form. With your consent, your enquiry may be shared with selected providers or brokers who may contact you; each provider decides whether to respond and sets its own eligibility, products and terms. An enquiry is not a loan application, quote or guarantee, and there is no obligation to proceed.
FundingMatch is not a lender or financier.
Frequently Asked Questions
What is the difference between invoice factoring and invoice discounting in Australia?
Factoring often involves the provider managing collections and notifying customers. Discounting tends to be confidential, with the business handling payments. Structures overlap, and terms differ by provider.
How quickly can I get funds?
Timing varies by provider and application.
Is this suitable for my trade business?
Possibly, if you invoice businesses on extended terms with solid histories. Discuss your specifics with providers.
Next Steps for Better Cash Flow
Slow-paying customers need not halt your momentum. Explore invoice finance Australia through a simple enquiry at FundingMatch. Gather your recent invoices and customer details to start conversations.
Disclaimer: This is general information only, not financial advice. Funding options depend on individual circumstances. Consult qualified professionals. Business purposes only; not for personal use or debt consolidation. Providers determine eligibility and terms.