What Do Lenders Look For in a Business Loan in Australia?
18 September 2025
Ever submitted a business loan enquiry in Australia only to hear crickets? You are not alone. Lenders review each case carefully. They check if your business can handle the loan.
This guide explains what do lenders look for business loan Australia. It covers common factors in Australian business loan assessment. Use it to prepare your SME credit assessment. Think of it as a map for your business finance enquiry Australia. It is general information only. Not a checklist for approval. Not legal or tax advice. This article focuses on business-purpose finance. It does not cover personal loans or residential mortgages.
Providers decide on their own terms. Criteria vary between lenders. An enquiry starts the conversation. It does not bind you or them.
The Business Itself
Lenders start with basics. They look at your business profile. First, your ABN. It shows registration date and activity. Has the business traded for six months? Two years? Longer histories often build trust.
Next, structure matters. Sole trader? Company? Trust? Partnership? Each has different rules. For companies, lenders may ask for director details. Like full names and roles. This helps verify setup with ASIC records.
Industry plays a role too. A construction firm differs from a retail shop. Lenders know sector risks. What about trading time? New startups face more scrutiny than established traders.
- ABN active and matching business name.
- Business structure clear on paperwork.
- Industry details straightforward.
- Time in operation noted.
Prepare these. It shows your SME credit assessment ABN is solid.
Capacity to Repay
Can your business pay back? This is key in what do lenders look for business loan Australia. They review recent trading.
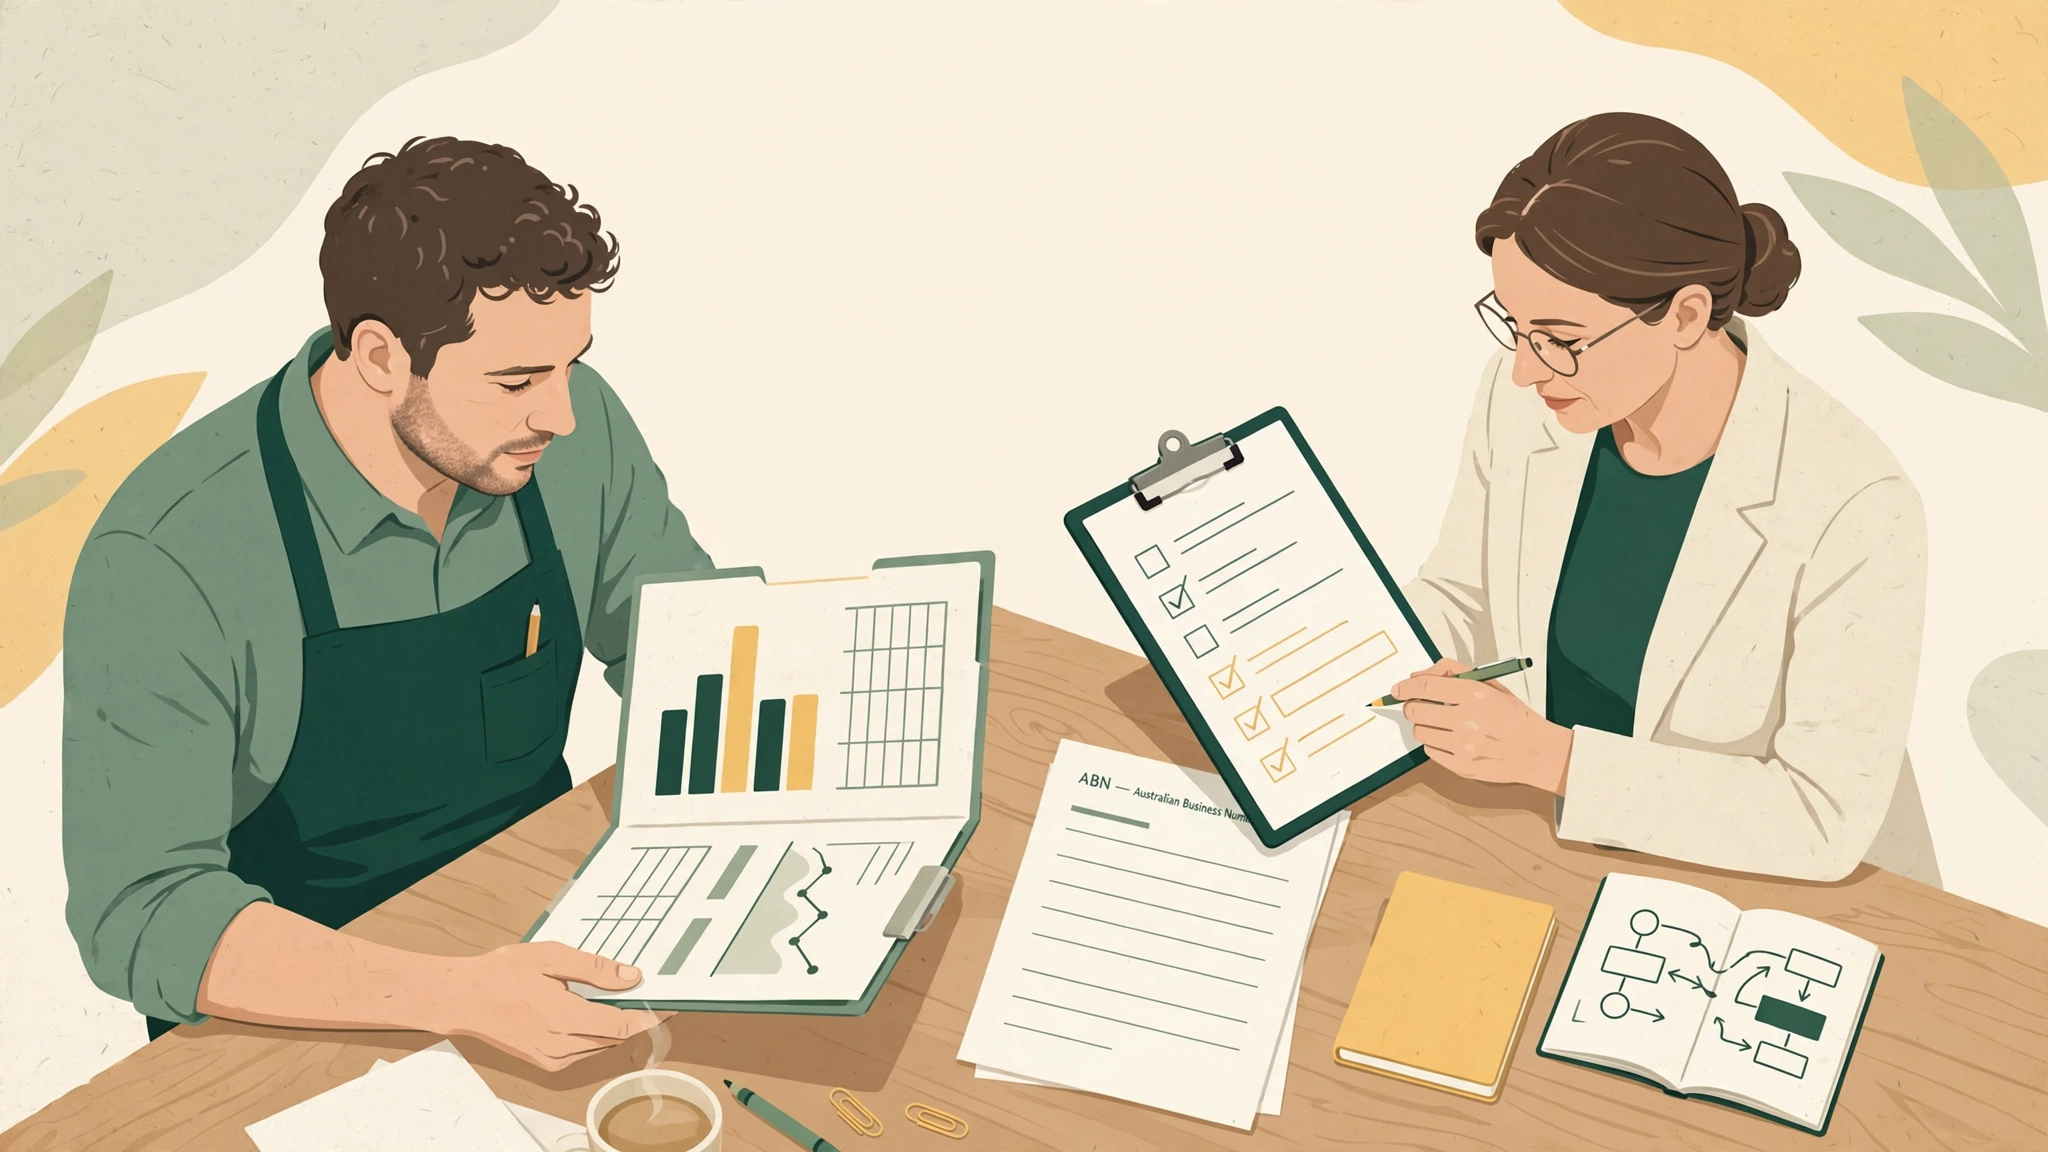
Bank statements come next. Commonly requested for three to six months. They reveal cash in and out. Steady deposits from customers? Regular supplier payments? This paints cash flow picture.
BAS and GST returns add detail. Quarterly lodgements show sales activity. High GST collections signal strong turnover. Low activity raises flags.
Existing debts count. Current loans or leases? Lenders factor these in. Cash flow means money left after bills to service new debt. Picture a workshop. Sales cover wages and rent. Enough remains for loan repayments? That is the test.
Gather statements and BAS. Help lenders see repayment strength.
Character and Completeness
Trust builds on history. Lenders check credit in general terms. Business and personal credit files. Consistent information across documents matters.
Gaps or mismatches? They slow things down. For companies or trusts, director credit may factor in. Some providers review guarantors too.
Full details upfront help. It shows you run a tight ship.
Security and Risk
Risk weighs heavy. Some facilities use assets as security. Equipment, vehicles, or property. Others do not. Providers choose based on their rules.
No one type fits all. Secured or not, each has pros and cons. Lenders balance this with other factors.
Purpose of Funds
Why the loan? Lenders want a clear business purpose. Equipment purchase? Inventory build? Bridging cash flow gaps? Growth plans?
Tie it to your trading life. A transport business buying trucks. A cafe fitting out a new site. Vague reasons get less traction. Specifics start better talks.
What Is a FundingMatch Enquiry?
FundingMatch is a starting point. Not a lender. Submit amount needed, purpose, and business profile. With consent, selected providers or brokers may respond.
It is not an application. No obligation to proceed. Just shares details to gauge interest. Providers assess each on their own.
Frequently Asked Questions
What is SME credit assessment ABN?
Lenders check your ABN for activity and trading history. It confirms business legitimacy.
How do bank statements factor into Australian business loan assessment?
They show cash flow patterns. Deposits and outflows reveal repayment ability.
Do all lenders require security?
No. Some facilities are secured. Others are not. It varies by provider.
What makes a strong business finance enquiry Australia?
Clear purpose, solid documents, consistent details. It invites responses.
Is FundingMatch a loan approval service?
No. With your consent, your enquiry may be shared with selected providers or brokers who may contact you; each provider decides whether to respond. They make decisions independently.
Prepared your details? Compare funding options. Submit a business funding enquiry today. Because providers assess each enquiry individually and a clear purpose helps the conversation start.
Disclaimer: This is general information. Not financial, legal, or tax advice. FundingMatch does not approve loans or set rates. Consult professionals for your situation.